
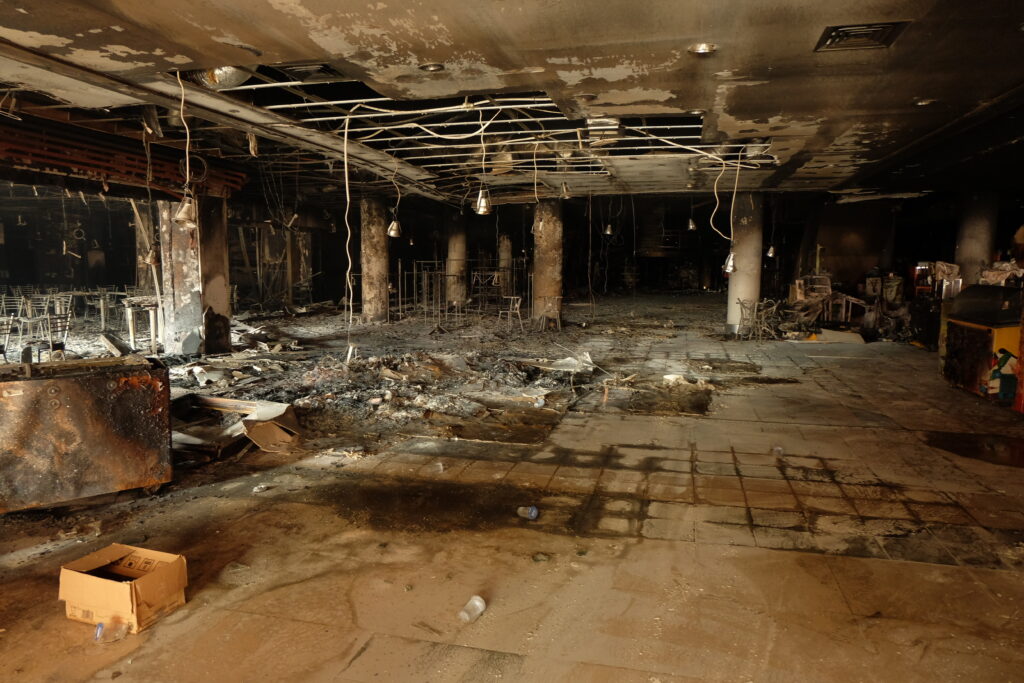
If you own commercial or residential property in Alaska, there’s a good chance the number on your insurance policy — the amount your insurer would pay to rebuild your property after a total loss — was never actually calculated by anyone qualified to calculate it.
That number matters more than almost any other figure on your policy. Get it wrong, and you don’t find out until the worst possible moment: after a fire, after a storm, after the property is gone and you’re trying to rebuild with a payout that falls tens or hundreds of thousands of dollars short.
Replacement cost isn’t market value — and it isn’t guesswork
Replacement cost is the amount it would take to rebuild a structure today, at current material and labor prices, with materials of similar kind and quality. It has nothing to do with what the property would sell for — location, land value, and market demand don’t factor in at all. It’s purely a construction cost question: what would it cost, today, to put this building back exactly as it was.
That distinction is exactly where things go wrong. A property’s market value and its replacement cost can differ by a wide margin, and an insurer, agent, or software tool that conflates the two — or that simply doesn’t have accurate construction cost data for the property’s specific type, quality, and finish level — can land on a number that’s badly off in either direction.
The real cost of getting it wrong
This isn’t a hypothetical risk — it’s a documented, widespread problem, and Alaska isn’t exempt from it.
Nationally, the numbers are stark. Multiple industry studies put the share of underinsured homes somewhere between 59% and 67%, meaning most American homeowners would come up short if they had to rebuild from a total loss today. A 2025 academic study from the University of Colorado and University of Wisconsin-Madison, examining nearly 5,000 policyholders who filed claims after Colorado’s Marshall Fire, found that 74% were underinsured — and more than a third of those were short by 25% or more of what it actually cost to rebuild. Researchers calculated the average shortfall at $139,000 per household. A separate industry estimate found that, on average, underinsured homeowners carry coverage for only about 78% of what it would actually cost to replace their home.
Part of the problem is where that number comes from in the first place. Industry commentary has pointed out that many agents provide quick quotes to close a sale, without the training to properly assess a home’s true rebuild cost, often relying on a short phone interview rather than an actual inspection or accurate cost data.
Alaska adds its own layer of risk on top of the national numbers. Statewide, residential construction now commonly runs $250 to $500+ per square foot, well above the roughly $150–$250 national average — driven by barge and air freight for materials, a short building season, and limited contractor capacity. A generic or outdated replacement cost figure doesn’t just miss by a little here; it misses by a lot. After the magnitude 7.1 earthquake that struck the Anchorage area in November 2018, homeowners across the region got a hard lesson in that gap. One Eagle River family’s roughly half-million-dollar home needed an estimated $300,000 in repairs — and initial federal disaster relief covered a small fraction of that. Another Anchorage homeowner, whose home was declared a total loss, described her shock at learning her earthquake deductible alone ran to 20% of her home’s insured value. These weren’t fringe cases — insurance claims spiked across the region in the weeks after the quake, and many homeowners learned only after the ground stopped shaking exactly how big the gap was between what they thought they had and what they actually needed.
That deductible detail matters beyond the earthquake context. Alaska earthquake deductibles typically run 10% to 20% of the insured value — meaning the replacement cost figure isn’t just what determines your payout after a total loss, it’s also what determines your out-of-pocket exposure before insurance even kicks in. An inaccurate replacement cost number doesn’t just risk a shortfall at claim time; it risks miscalculating what you’re actually on the hook for out of pocket.
Locally, insurance agents doing their own replacement cost estimates is common — and it’s common for those estimates to be wrong. Agents aren’t trained to grade construction quality, correctly classify occupancy type, or account for the finish-level and fixture details that drive real cost differences in professional-grade cost estimating software. It’s not unusual for an agent, after getting an estimate they’re not confident in, to tell a client to go get an appraisal instead.
At the same time, a growing number of unlicensed, non-appraiser services are selling cheap replacement cost estimates generated from that same category of software — without the training to use it correctly. The tool itself is only as good as the person running it, and getting it right takes real time and expertise, not just data entry.
RVS uses industry-recognized, best-in-class cost data — the same caliber of resource relied on by lenders, insurers, and appraisers nationwide, and one piece of the broader toolkit RVS uses to develop the depreciated cost approach in our own commercial and residential appraisal work. We don’t reach for the cheap or free alternatives. Our appraiser holds specific training in this software, backed by decades of experience applying it to both everyday and high-stakes appraisal assignments — the difference between running the numbers and knowing what the numbers should actually say.
Why a CMA or BPO is the wrong tool for this
One mistake worth calling out directly: a Comparative Market Analysis (CMA) or Broker Price Opinion (BPO) from a real estate agent is not a substitute for a replacement cost estimate — and using one for insurance purposes can be worse than using nothing at all, because it creates false confidence in a number that was never designed to answer this question.
A CMA or BPO exists to estimate what a property would sell for, based on recent comparable sales in the market. It has no cost-approach component at all — no analysis of construction type, materials, labor costs, or what it would actually take to rebuild the structure from the ground up. It bakes in land value and market conditions, neither of which has anything to do with rebuild cost. Two homes could sell for wildly different prices based purely on lot location and market demand, while costing nearly identical amounts to reconstruct — a CMA or BPO would never surface that. It’s built by a real estate agent or broker, not an appraiser, and it isn’t accepted by lenders or courts for any purpose that requires an actual valuation. Using a sales-comparison tool to answer a construction-cost question isn’t just imprecise — it’s the wrong tool for the job entirely, no matter how well it’s executed.
The “bank minimum” trap for commercial owners
There’s a commercial-specific version of this problem that’s especially common — and especially costly. Many commercial property owners carry insurance sized to satisfy their lender, not to actually cover the building. In practice, that often means coverage set at or near the outstanding loan balance, because that’s the number the bank asked for and the number that gets the loan closed.
The problem: a lender’s minimum exists to protect the lender’s collateral position, not the owner’s equity. If a building is worth more than what’s owed on it — which is the entire point of building equity over time — insuring only to the loan balance leaves the owner personally exposed for the difference in a total loss. A business that’s paid down a $2 million loan to $1.2 million on a building that would actually cost $2.5 million to rebuild could be left with a $1.2 million payout and a $2.5 million rebuild cost, with the owner absorbing the $1.3 million gap out of pocket — even though the loan itself gets satisfied.
It’s also worth noting that most lenders’ own requirements are written to call for full replacement cost coverage, not simply the loan balance — a half-rebuilt building doesn’t fully secure their collateral either. In practice, though, agents and borrowers often default to whatever figure satisfies the minimum requirement on paper, which isn’t always checked against actual rebuild cost.
There’s a second, sharper problem hiding in most commercial policies: the coinsurance clause. Most commercial property policies require coverage equal to 80% or 90% of the building’s actual replacement cost. Fall short of that threshold, and the insurer doesn’t just risk being short on a total loss — it pays out only a proportional share of any claim, even a small one. Insure a building for 60% of what it would actually cost to rebuild under a 90% coinsurance requirement, and a routine partial loss — a roof fire, a burst pipe, storm damage to one section — gets paid at roughly two-thirds of the actual claim amount, not the full amount. One industry estimate puts the scale of this problem bluntly: roughly three-quarters of commercial properties nationwide are underinsured, by an average of nearly 50%. Commercial replacement costs have also risen sharply industry-wide in recent years, and most commercial policies haven’t been updated to keep pace — meaning coverage that was adequate a few years ago may already be significantly behind.
For a commercial property owner, the fix isn’t complicated: know your building’s actual replacement cost, separately from whatever number satisfies the bank, and make sure your coverage reflects it — not just the balance on the note.
What RVS now offers
RVS has developed a replacement cost estimate service, built on that same professional-grade cost data and produced by an appraiser experienced in cost approach methodology — bridging the gap between a free-but-unreliable agent estimate and the cost of a full commercial or residential appraisal.
This is not an appraisal. It does not include an opinion of market value, is not prepared under USPAP, and should not be represented as an appraisal for lending, legal, or other purposes that require one. It is a standalone cost estimate, intended specifically to support insurance coverage decisions.
Two ways to get one:
- Desktop estimate (available nationwide): the client completes an intake form covering construction type, plumbing fixture count, siding, interior finishes, and other cost-relevant details, and provides a sketch or building plans. RVS uses that information to develop the estimate.
- Site visit option (Alaska only): RVS visits the property to measure and confirm construction type, fixtures, and finishes directly, rather than relying on the client’s own documentation. This is a measurement and confirmation visit only — not a market value inspection. It’s particularly valuable for older properties or ones with additions and remodels over the years, where a client-supplied sketch may not fully capture what’s actually there.
Pricing
Pricing starts at $500 for residential properties and $850 for commercial properties (desktop estimate, one construction section), with additional sections, outbuildings, and an optional Alaska site visit priced separately depending on the property. Most residential properties, even with added complexity, come in well under $1,000 — most commercial properties have more than one section, so plan on a bit more. See full pricing details or contact RVS for a firm quote on your specific property.
Before your next renewal
If your last replacement cost figure came from an agent’s software estimate, a rough per-square-foot guess, or an online calculator, it’s worth having it checked before you’re relying on it after a loss instead of before one. It’s also worth revisiting anytime the property itself changes — an addition, a remodel, a finish upgrade, or a new outbuilding all shift the number, and an inflation-guard endorsement alone often doesn’t keep pace with Alaska-specific cost increases. Request a quote to get a replacement cost estimate you can trust.
References
- University of Colorado Boulder / University of Wisconsin-Madison, “Coverage Neglect in Homeowners Insurance” study on Marshall Fire claims, 2025
- United Policyholders, underinsurance analysis following the Marshall Fire
- Industry data on national homeowner underinsurance rates (various industry surveys and insurance-industry cost-data providers)
- Anchorage Daily News, coverage of the November 2018 Anchorage earthquake and earthquake insurance
- GovTech / Alaska news coverage, one-year retrospective on 2018 Anchorage earthquake recovery
- FEMA, 2018 Alaska earthquake disaster assistance figures
- Alaska residential construction cost data, 2025–2026 market guides
- Industry data and commentary on commercial property coinsurance requirements and underinsurance rates